NRI Guide to Buying a Luxury Home in Gurugram
Buying in Gurugram from abroad? A plain-English NRI guide to payments, loans, Power of Attorney, RERA checks, taxes and the mistakes to avoid.
Buying a home in India from Dubai, London, Singapore or New Jersey is very doable. Plenty of my clients have done it without setting foot in Gurugram until the keys were ready. But it does work differently from buying locally. The money has to move a certain way, the paperwork has a few extra steps, and someone you trust may need to sign on your behalf.
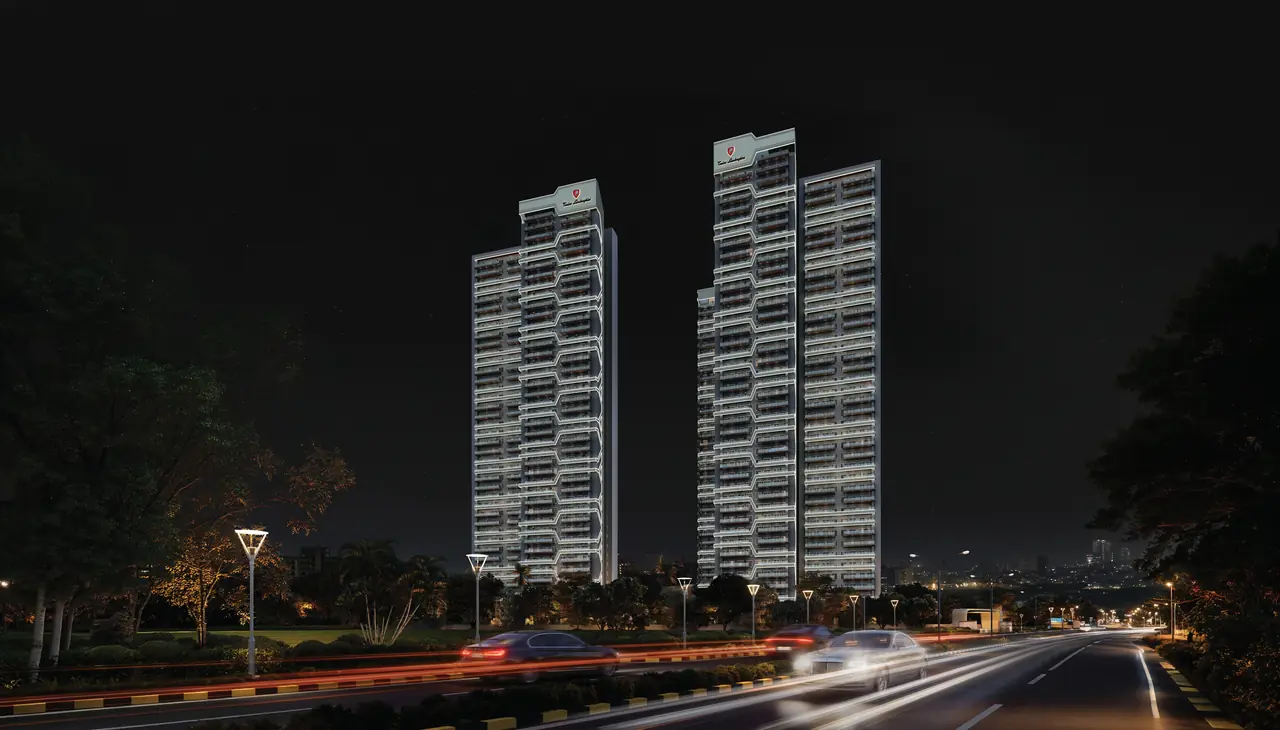
This guide walks you through the process using Tonino Lamborghini Residences Gurugram in Sector 71 as the example. I will keep the regulatory parts general, because rules get updated and your personal tax position is yours alone. Wherever tax or repatriation comes up, please run it past a chartered accountant who works with NRIs. That is not a disclaimer for the sake of it. It genuinely saves people money.
Can you buy? NRI, OCI and what the rules allow
Under India's foreign exchange rules (FEMA), a Non-Resident Indian is an Indian citizen who lives outside India. An Overseas Citizen of India (OCI) cardholder is a person of Indian origin who holds a foreign passport and an OCI card.
The good news is simple. Both NRIs and OCI cardholders generally have permission to buy residential and commercial property in India without needing separate approval from the Reserve Bank of India. There is no cap on the number of residential properties you can buy under this general permission.
The main exclusions are agricultural land, plantation property and farmhouses. Those are off the table for purchase, though inheritance is treated differently. A luxury apartment in a licensed residential colony, which is what this project is, sits squarely in the permitted category.
If you hold a foreign passport but do not have an OCI card, the position is different and more restrictive. Speak to a lawyer before you go any further.
How the money must move, and home loans
This is where people trip up, so read it twice. Payments for the property have to come through normal banking channels. In practice that means one of these:
- Inward remittance from your overseas bank account to India
- NRE account (Non-Resident External): holds money earned abroad, in rupees, and is generally repatriable
- FCNR(B) account: a fixed deposit held in foreign currency
- NRO account (Non-Resident Ordinary): holds income earned in India, such as rent, dividends or pension
Cash, traveller's cheques and foreign currency notes are not acceptable modes of payment. And paying from a relative's resident account to "keep things simple" creates headaches later, especially when you want to sell and take money back out.
Why the source of funds matters later
The account you pay from today shapes how easily you can repatriate the money when you sell. Paying from NRE, FCNR or direct inward remittance generally gives you a cleaner trail for repatriation. Keep every bank advice, FIRC or remittance confirmation in one folder. Future you will be grateful.
Home loans for NRIs
Most major Indian banks and housing finance companies lend to NRIs for buying residential property. The loan is in rupees and is disbursed in India, usually directly to the developer as construction progresses.
A few general points worth knowing:
- Repayment usually comes from your NRE or NRO account, or through inward remittance.
- Lenders will want proof of overseas income, employment, visa or residency status, and often a credit report from your country of residence.
- Some lenders ask for a resident co-applicant or a local Power of Attorney holder to handle paperwork.
- Loan-to-value ratios, interest rates and tenure vary by lender and change often. Compare at least two or three.
My practical tip: get your loan sanctioned in principle before you book. With an instalment plan, a loan delay on one milestone can turn into late-payment interest very quickly.
Power of Attorney and paperwork
You do not have to fly in for every signature. A Power of Attorney (PoA) lets someone you trust, usually a parent, sibling or close friend, act for you in India.
Here is how it usually works:
- Get the PoA drafted by an Indian lawyer, specific to this purchase. A specific PoA is safer than a general one.
- Sign it abroad and have it attested at the Indian embassy or consulate, or notarised and apostilled if your country is part of the Hague Convention.
- Once it reaches India, it needs to be stamped and adjudicated with the local authorities within the prescribed time.
Be precise about what the PoA covers: signing the builder buyer agreement, registration, dealing with the bank, taking possession. And choose your attorney carefully. A PoA is a lot of trust in one piece of paper.
Documents you will typically need
Requirements vary between developers, banks and the registrar, but this list covers most of it:
- Passport and visa or residence permit copies (OCI card if applicable)
- PAN card. If you do not have one, apply early, because nothing moves without it
- Overseas address proof and Indian address, if any
- Passport-size photographs
- NRE/NRO bank statements and remittance records
- Power of Attorney, if someone is signing for you
- Income documents, if you are taking a loan
Check the project, then see it from afar
For any under-construction project in Haryana, the first stop is HRERA. Tonino Lamborghini Residences Gurugram is registered under HRERA Registration RC/REP/HARERA/GGM/1056/788/2026/28, dated 08.04.2026. The developer is Signatureglobal (India) Limited, listed on NSE and BSE.
Look the number up yourself on the HRERA Gurugram portal. Check the registered promoter, the land details and the approvals. The project also holds DTCP Licence No. 187 of 2025, with the building plan approved on 03.03.2026. You will notice that no possession date is published in the material I work from, and I will not guess one for you. Ask the developer what the RERA filing states and get it in writing.
For more on how this stage of buying compares with a finished home, read under-construction vs ready luxury homes.
Seeing the home when you are 7,000 km away
You cannot judge a home from a brochure, but you also do not need to be physically present for every step. Here is what works:
- Live video walkthrough of the sales gallery and sample spaces. Ask for it on a proper video call, not a pre-recorded reel, so you can say "turn left, show me that".
- A trusted family visit. Send a parent or friend with a checklist. The site visit checklist is written for exactly this.
- Location homework on maps: drive times to Golf Course Road, Cyber Hub and the airport route. The location page gives approximate timings.
- Floor plans and orientation sent to you as files, so you can study them in your own time.
If you are visiting India anyway, plan one in-person visit to the Sector 71 sales gallery. It is by appointment, so you will not waste a day.
The 25:25:25:25 plan and currency planning
The payment plan currently offered is 25:25:25:25, which means the price is paid in four instalments of 25 per cent each. The plan can change by phase, so confirm the current milestones before you book. Phase 1 was announced sold out in early November 2026, and Phase 2 is expected soon.
To put the scale in context, indicative prices on the channel-partner sheet start around ₹4.80 crore for a 3 BHK of roughly 2,100 sq ft, before GST, stamp duty, registration and other charges. The current figures are on the price list.
Why currency matters more than you think
If your income is in dollars, dirhams or pounds, every instalment is a currency conversion. The rupee can move meaningfully between your first and last payment, and that cuts both ways.
- Know roughly when each instalment will fall due.
- Consider parking funds in your NRE or FCNR account ahead of a milestone, so you are not forced to convert on a bad day.
- Compare remittance charges and exchange spreads across your banks. Small differences add up on crore-sized payments.
I am not giving you investment advice here, just a reminder to plan the cash flow rather than react to it.
Taxes and repatriation: the general picture
Please read this section as an outline, not a tax opinion. India's income tax law was rewritten under the Income-tax Act, 2025, and section numbers have changed, so your CA's advice matters more than ever.
When you buy
When you buy property worth ₹50 lakh or more from a resident seller, which includes an Indian developer, the buyer generally has to deduct TDS of 1 per cent and deposit it with the government. GST applies on under-construction homes, and stamp duty and registration are paid at the time of registration. Your CA or the developer's team can help you file correctly.
When you rent it out
Rental income from an Indian property is taxable in India. If you are an NRI landlord, your tenant is usually required to deduct tax at source before paying you, which surprises many tenants. You may also need to file an Indian tax return. Depending on where you live, a tax treaty may affect how that income is treated abroad.
When you sell
Capital gains tax applies, and the rules depend on how long you have held the property. When the seller is an NRI, the buyer has to deduct TDS at a much higher level than the 1 per cent that applies to resident sellers. It is possible to apply for a lower deduction certificate. Plan this well before you sign a sale deal.
Taking money back out
Under the general RBI framework, NRIs can usually repatriate sale proceeds of up to two residential properties, broadly limited to the amount originally paid in foreign exchange or from NRE/FCNR accounts. Money sitting in an NRO account can also be repatriated within an annual limit, after taxes and with the required CA certificates. The details are specific, so confirm with your CA and your bank before you assume anything.
Your step-by-step checklist, and mistakes to avoid
- Confirm your status (NRI or OCI) and that a PAN card is in place.
- Open or check your NRE/NRO account, and decide where the funds will come from.
- Talk to a CA who handles NRI property and tax.
- Get a home loan sanctioned in principle, if you need one.
- Verify HRERA registration and approvals on the official portal.
- Do a live video walkthrough and, ideally, a family visit.
- Shortlist the unit by floor plan, orientation and floor.
- Get a specific Power of Attorney drafted and attested, if you need one.
- Book through banking channels and keep every remittance record.
- Read the builder buyer agreement with a lawyer before signing.
- Calendar each instalment and plan your currency conversions.
Mistakes I see NRIs make
- Paying from a relative's resident account. It feels easier, but it muddies the paper trail and can make repatriation harder later.
- Signing a general PoA. Keep it specific to the transaction.
- Trusting a possession date said over the phone. Only rely on what is in the RERA filing and the agreement.
- Ignoring the all-in cost. GST, stamp duty, registration, PLC and parking can add materially to the base price.
- Leaving tax to the end. TDS, rental tax and capital gains are far easier to manage when planned at purchase.
- Buying on brand alone. A famous name on the facade is lovely, but it does not replace checking the developer, the approvals and the agreement.
A sensible next step
If this project is on your shortlist, the easiest start is a 30-minute video call. We can walk through floor plans, the current payment plan and Phase 2 timing at a time that suits your time zone. If family in India can visit, we will set up an appointment at the Sector 71 sales gallery for them. Reach us through the contact page, or call or WhatsApp +91 98114 78909. No pressure, just answers.